How Much Will $10,000 Grow in 10, 20 and 30 Years?
How much will $10,000 grow if you leave it alone for 10, 20 or 30 years? $10,000 is a common starting point: an inheritance, a work bonus, a tax refund saved up or several years of careful saving. The answer depends on two things you can see clearly in this guide: the yearly return and how long you give it.
Quick answer
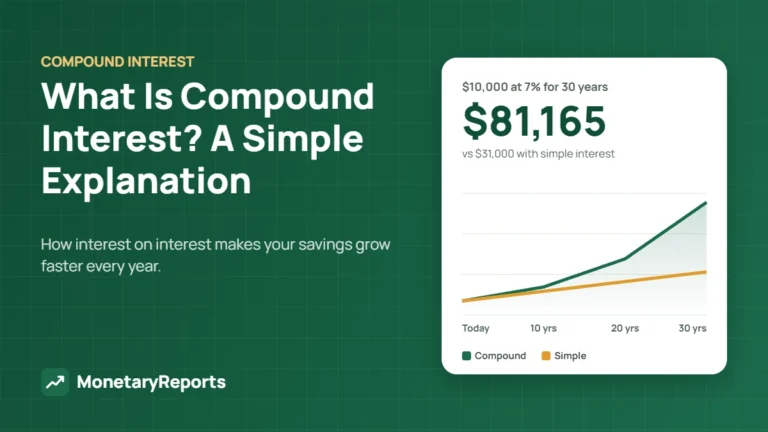
Short answer to “how much will 10000 grow”: at 7% a year (compounded monthly), $10,000 grows to about $20,097 in 10 years, $40,387 in 20 years and $81,165 in 30 years, with no extra deposits. At 4% it reaches about $33,135 after 30 years; at 10% about $198,374.
How much will $10,000 grow at different rates?
| Yearly rate | After 10 years | After 20 years | After 30 years |
|---|---|---|---|
| 4% | $14,908 | $22,226 | $33,135 |
| 5% | $16,470 | $27,126 | $44,677 |
| 6% | $18,194 | $33,102 | $60,226 |
| 7% | $20,097 | $40,387 | $81,165 |
| 8% | $22,196 | $49,268 | $109,357 |
| 10% | $27,070 | $73,281 | $198,374 |
If interest is added only once a year (annual compounding), the results are a little lower. At 7% you would have about $76,123 after 30 years instead of $81,165.

The first 5 years
Many people want to know what happens in the short term, for example before buying a house or a car.
| Yearly rate | After 5 years | Growth |
|---|---|---|
| 4% | $12,210 | +$2,210 |
| 5% | $12,834 | +$2,834 |
| 6% | $13,489 | +$3,489 |
| 7% | $14,176 | +$4,176 |
| 8% | $14,898 | +$4,898 |
| 10% | $16,453 | +$6,453 |
For money you need within 5 years, many people prefer savings accounts or CDs, because stocks can fall in value just when you need the cash.
Interactive chart
Hover or tap the chart to compare three rates year by year.
Interactive chart: hover or tap to see each year. Estimates only, before taxes and inflation.
Why the last 10 years matter most
At 7%, your $10,000 gains about $10,097 in the first 10 years, about $20,290 in the next 10 and about $40,778 in the last 10. Each decade earns roughly twice as much as the one before, because the balance doing the earning is twice as big. At that pace it takes about 33 years for $10,000 to reach $100,000 on its own.
The lesson is simple: time does most of the work. Taking money out early, even once, removes the base that later growth depends on.
What if you add money every month?
Regular deposits change the picture completely. Here is $10,000 at 7% with an extra $100 or $200 a month:
| After | Only $10,000 | + $100/month | + $200/month |
|---|---|---|---|
| 10 years | $20,097 | $37,405 | $54,714 |
| 20 years | $40,387 | $92,480 | $144,573 |
| 30 years | $81,165 | $203,162 | $325,159 |
Try it with your own numbers
Enter your own starting amount, monthly deposit, rate and years.
3 ways to use $10,000
- High-yield savings account at 4% APY: about $14,802 after 10 years if the rate stayed the same. Low risk and easy access, FDIC-insured up to the legal limit, but rates can drop at any time.
- 5-year CD at 4.5% APY: about $12,462 after 5 years. The rate is fixed, but you may pay a penalty if you withdraw early.
- Diversified stock index fund: historically higher long-term growth, which is where 7% planning assumptions come from, but values can fall 20% or more in a bad year. Best for money you will not need for many years.
Many people split the money: an emergency fund in savings first, then long-term money invested. This is general information, not a recommendation for your situation.
How much will $10,000 grow after inflation, taxes and fees?
The numbers above are “nominal”: they do not account for rising prices. If inflation averages 3% a year, here is what the 7% results would buy in today’s money:
| After | Nominal balance at 7% | In today’s dollars (3% inflation) |
|---|---|---|
| 10 years | $20,097 | $14,954 |
| 20 years | $40,387 | $22,362 |
| 30 years | $81,165 | $33,439 |
- Taxes: interest and investment gains are often taxable unless they are held in a tax-advantaged account such as a 401(k) or IRA.
- Fees: a 1% yearly fee reduces a 7% return to about 6%, which at 30 years means about $60,226 instead of $81,165.
What $10,000 means for you, by goal
- Emergency fund: keep it in an FDIC-insured high-yield savings account; growth is a bonus, safety and access come first.
- Home down payment in 3 to 5 years: savings accounts, CDs or Treasury bills are common choices, because a market drop right before you buy could hurt.
- Retirement in 20+ years: this is where a long-term, diversified investment has the most time to compound, ideally in a tax-advantaged account.
Common mistakes
- Using one “magic” rate. Try a cautious rate and an optimistic one to see a range instead of a single number.
- Investing money you will need soon. Short-term money and stock market swings do not mix well.
- Leaving it in a 0.01% checking account. Cash that earns almost nothing loses value to inflation every year.
- Selling after a bad year. Long-term results depend on staying invested through the ups and downs.
Frequently asked questions
How long does it take $10,000 to double?
Use the Rule of 72: divide 72 by the yearly rate. At 7% it takes a little over 10 years; at 4% about 18 years; at 10% about 7 years. Each doubling after that takes the same amount of time, which is why the balance accelerates.
How much will $10,000 be worth in 5 years?
At 5% compounded monthly, about $12,834. At 7%, about $14,176. In a savings account the result depends on the APY, which can change over time, so check current rates before you decide.
Is it better to invest $10,000 at once or monthly?
If the money is already available and you will not need it for many years, investing it sooner gives it more time to compound. Spreading it over several months can reduce the stress of investing just before a market drop. Both are reasonable; it depends on your situation and comfort with risk.
How much will $10,000 grow in a savings account?
At 4% APY, about $12,167 after 5 years and $14,802 after 10 years, if the rate stayed the same. At a 0.4% APY, the same $10,000 would only reach about $10,202 after 5 years, so the account you choose matters.
Are these results guaranteed?
No. They assume the same rate every year. Savings rates change with the economy, and investments go up and down. Treat these numbers as a planning guide, not a promise.
How can I turn $10,000 into $100,000?
At 7% a year with no extra deposits, it would take about 33 years. Adding $200 a month gets you past $100,000 in less than 20 years: about $144,573 after 20 years. Regular deposits are usually the fastest lever you control.
How much will 10000 grow in 20 years?
At 7% a year compounded monthly, $10,000 grows to about $40,387 in 20 years with no extra deposits. At 5% it would be about $27,126, and at 10% about $73,281. Adding $200 a month at 7% would bring the 20-year total to about $144,573.
Related guides and calculators
- How much will $1,000 grow in 10 years?
- What $100 a month becomes in 30 years
- Rule of 72 calculator
- Interest calculator
Sources
- Investor.gov (U.S. SEC): Compound interest calculator
- U.S. Bureau of Labor Statistics: Consumer Price Index
- FDIC: National rates and rate caps
- MonetaryReports: How we calculate
This guide is for educational purposes only and is not financial advice. The figures are estimates before taxes, fees and inflation, and real savings rates and investment returns change over time.